Let us help you grow the business you love.
Your world is about to get a whole lot simpler.

Most conversations about community debt naturally focus on the arrears themselves: how much is outstanding, who owes it, how long it has been outstanding and what is being done to recover it.
These are essential questions for effective debt management, but they leave another critical question unanswered:
What does that debt position mean for the financial resilience of the community carrying it?
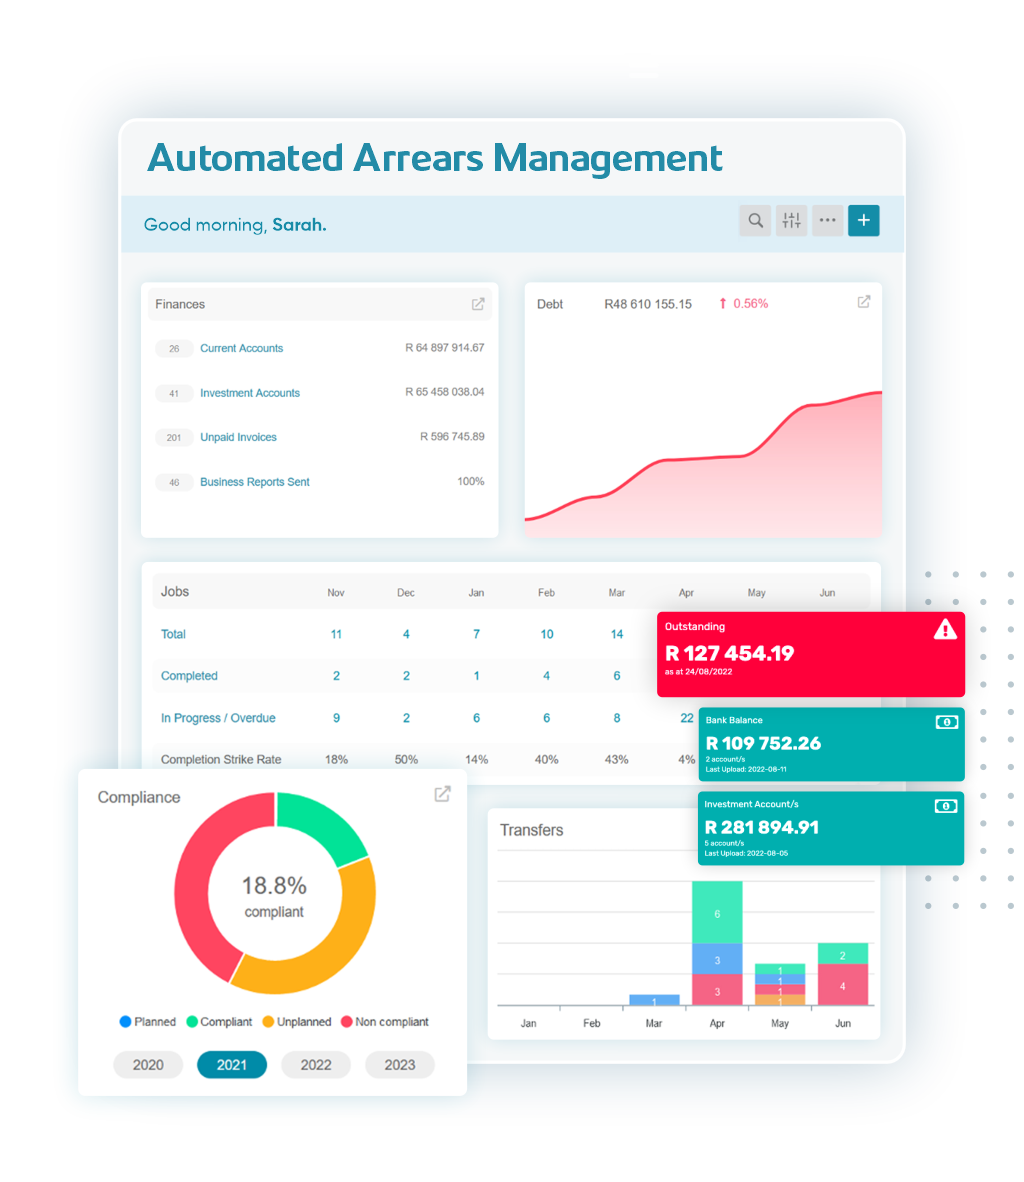
Consider two communities, each carrying R500,000 in outstanding debt.
For one, that R500,000 might represent a relatively small portion of its expected levy income. For the other, it could represent several months’ worth.
The rand value is identical. The potential financial impact is not.
Levies are the income a community relies on to fund its operations, meet its obligations and carry out its plans. When some of those levies aren't paid, the community has less cash available than expected.
Its ability to keep operating effectively, despite that shortfall, is a measure of its financial resilience.
For a Community Asset Manager, that resilience matters because it directly affects the community’s ability to protect and improve its long-term asset value.
So, understanding debt starts with putting the amount outstanding into proportion. But even that only tells us how significant the exposure is. It doesn't tell us whether that position is typical for a community like ours, why we might be carrying more or less debt than comparable communities, or what other aspects of the community's finances might help explain the difference.
Those are much harder questions to answer when the only data available is your own.
The South African Asset Intelligence Report we are currently developing is intended to give Community Asset Managers a new way to bridge that information gap.
Our emerging benchmark shows that outstanding community debt currently equates to an average of 4.21 months of levies. That’s a useful reference point for analysing individual communities’ debt exposure, but the real value lies in what can be investigated around it.
The benchmark we are developing is intended to make it possible to consider debt alongside broader industry statistics across communities of different sizes and metropolitan regions. This will enable Community Asset Managers to compare multiple measures, including debt and levy levels, and use the relationships they uncover to guide further investigation.
If a community carries materially more debt than comparable communities, for example, how do its levies compare? If both are comparatively high, affordability may be worth investigating. Is the community trying to fund a level of expenditure that its owners are struggling to sustain? Do the assumptions behind the budget need another look?
If levy levels appear broadly comparable but debt remains unusually high, the investigation may head elsewhere. Are collections as effective as they could be? Is the debt concentrated among a small number of owners? Is there something particular about the community that helps explain the difference?
A comparatively strong debt position can be informative too. It can give Community Asset Managers independent context for understanding financial performance and a more objective way to demonstrate sound financial stewardship to trustees.
As the benchmark develops, this kind of industry context can give Community Asset Managers a stronger starting point for understanding what may be shaping their community’s financial position and where further investigation may be valuable.
The goal isn't simply to drive debt as close to zero as possible. It’s to build a realistic financial plan around what the community needs to fund, what its owners can sustainably afford and what it can reasonably expect to collect.
That may mean strengthening debt-management processes. It may mean interrogating expenditure or reconsidering the assumptions behind the budget. It may simply confirm that the community is in a comparatively strong financial position and that the current approach is working well.
For Community Asset Managers, this is where debt information starts contributing to something much bigger than arrears management. Better-informed financial decisions support the community’s ability to remain resilient, meet its obligations and protect and improve the long-term value of its shared asset.
It also illustrates the evolution from Community Management to Community Asset Management. Managing the debt remains essential. But the greater professional opportunity lies in interpreting what that debt tells us, bringing wider context to the conversation and using that understanding to help trustees make better decisions about the community and its assets.
And debt is only one example of what becomes possible when community-specific knowledge is combined with broader industry intelligence.
There is still work to be done as we refine the benchmark and bring the broader industry context together. As this initiative develops, we look forward to sharing more about how Asset Intelligence can help Community Asset Managers make stronger, evidence-based decisions and ultimately become more valuable in the service they deliver and more valued for the outcomes they create.